UPI Charges 2026: Will You Have to Pay for UPI?
India’s UPI payment system is set to see changes in the way certain merchant transactions are charged from October 15, 2026.
The introduction of a Merchant Discount Rate (MDR) on selected UPI transactions above ₹2,000 has created confusion among consumers about whether they will now have to pay a fee when making UPI payments.
The important point is that the MDR is a merchant-side charge, not a fee directly collected from the customer.
Person-to-person UPI transfers will continue to remain free, while eligible merchant transactions up to ₹2,000 will also remain free under the framework described in the report.
🧾 What Is MDR?
MDR stands for Merchant Discount Rate.
It is a fee associated with accepting digital payments and is charged within the merchant-payment ecosystem.
Under the new framework, certain standard Person-to-Merchant (P2M) UPI transactions above ₹2,000 will attract an MDR of 0.4%.
For transactions of ₹75,000 and above, the MDR is capped at ₹300 per transaction.
Importantly, the customer is not supposed to be separately charged this MDR by the merchant under the stated framework.
👤 Will Customers Have to Pay UPI Charges?
No.
The reported framework does not introduce a general customer fee for making UPI payments.
This means consumers can continue to use UPI for routine payments without a separate UPI transaction charge being deducted from their bank accounts.
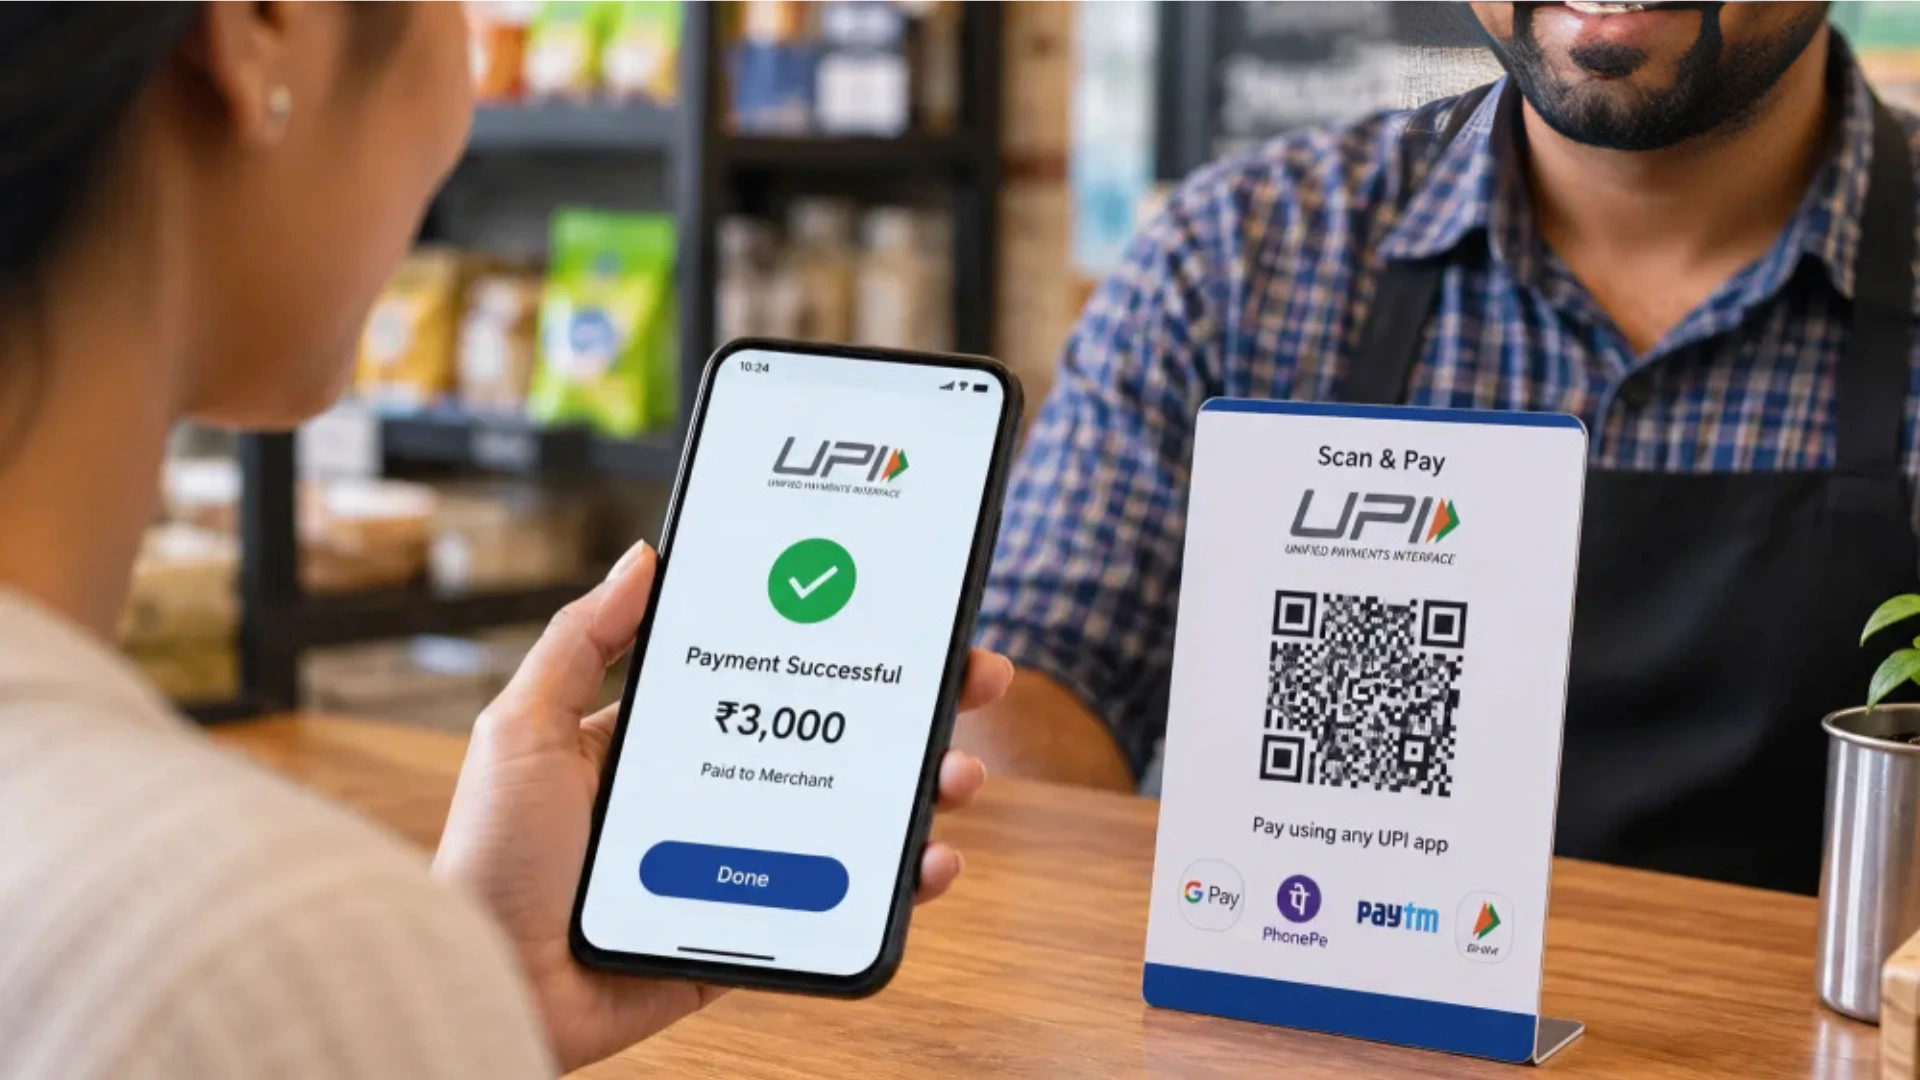
For example, if a customer buys a product worth ₹5,000 and pays through UPI, the customer pays the ₹5,000 displayed by the merchant.
The applicable MDR is handled within the merchant/payment ecosystem.
💰 What Happens When You Pay ₹5,000 Through UPI?
Let’s understand the new MDR with a simple example.
For a standard eligible merchant transaction of ₹5,000:
0.4% of ₹5,000 = ₹20
Therefore, the applicable MDR would be ₹20, subject to the rules applicable to that merchant category.
Important point:
The customer does not pay ₹5,020.
The customer continues to pay the merchant’s listed price of ₹5,000.
💵 What Happens When You Pay ₹50,000?
For a standard eligible merchant transaction of ₹50,000:
0.4% of ₹50,000 = ₹200
Therefore, the calculated MDR would be ₹200.
Again, this is a merchant-side payment ecosystem charge.
The customer does not pay an additional ₹200 simply because the payment was made through UPI.
💰 What Happens When You Pay ₹1 Lakh?
This is where the MDR cap becomes important.
For a ₹1,00,000 eligible transaction:
0.4% of ₹1,00,000 = ₹400
However, the framework places a maximum MDR cap of ₹300 for transactions of ₹75,000 and above.
Therefore:
₹1,00,000 UPI payment → ₹300 maximum MDR
The customer still pays the merchant’s listed price of ₹1,00,000, rather than ₹1,00,300.
📊 UPI MDR Examples at a Glance
| UPI Payment | Standard MDR Calculation | Applicable MDR* | Customer’s Listed Payment |
|---|---|---|---|
| ₹2,000 | No MDR | ₹0 | ₹2,000 |
| ₹5,000 | 0.4% = ₹20 | ₹20 | ₹5,000 |
| ₹50,000 | 0.4% = ₹200 | ₹200 | ₹50,000 |
| ₹75,000 | 0.4% = ₹300 | ₹300 | ₹75,000 |
| ₹1,00,000 | 0.4% = ₹400 | ₹300 cap | ₹1,00,000 |
*For standard eligible P2M transactions; special merchant categories can have different rates.
🛍️ What About UPI Payments Below ₹2,000?
Eligible merchant transactions up to ₹2,000 remain outside the new standard MDR charge described in the framework.
For example:
- ₹500 → No MDR
- ₹1,000 → No MDR
- ₹2,000 → No MDR
- ₹2,001 → Standard MDR framework may apply
The exact treatment can depend on the merchant category and applicable UPI rules.
🏪 What Does This Mean for Small Merchants?
The new MDR framework is primarily relevant to merchants accepting UPI payments.
The government has stated that around 96% of merchant UPI transactions will remain unaffected by the changes.
For merchants whose transactions fall under the applicable MDR categories, the cost of accepting certain higher-value UPI payments will change.
However, merchants are not supposed to simply add the MDR as a separate UPI surcharge to the customer’s bill under the stated rules.
🚆 Special Categories Have Different MDR Rates
Not every UPI payment above ₹2,000 will necessarily attract the standard 0.4% rate.
Certain specified sectors have separate MDR provisions.
These include categories such as:
- Railways
- Telecommunications
- Insurance
- Fuel
For specified eligible transactions in these categories, the framework provides a flat ₹5 MDR rather than the standard 0.4% rate.
Therefore, consumers should not assume that every UPI transaction above ₹2,000 automatically means a 0.4% merchant charge.
📈 What Happens When You Pay for Mutual Funds or Stocks?
Capital-market transactions have a separate MDR structure.
According to the reported NPCI framework, payments involving categories such as:
- Mutual funds
- Securities
- Stockbrokers
- Securities dealers
- Investment platforms
can attract an MDR of 0.02%, subject to a maximum of ₹300 per transaction.
This means these payments are treated differently from ordinary retail merchant purchases.
📊 Example: ₹1 Lakh Mutual Fund Payment
Suppose an eligible capital-market transaction is worth ₹1,00,000.
At an MDR of 0.02%:
₹1,00,000 × 0.02% = ₹20
Therefore, the calculated MDR would be ₹20, subject to the applicable rules and cap.
Again, this does not mean the customer automatically pays an additional ₹20 as a UPI fee.
👨👩👧 What About Sending ₹1 Lakh to a Family Member?
This is an important distinction.
If you transfer ₹1 lakh to another person’s bank account through a normal Person-to-Person (P2P) UPI transfer, the merchant MDR framework does not turn that transfer into a paid transaction.
For example:
You → Send ₹1,00,000 → Family member
This is fundamentally different from:
You → Pay ₹1,00,000 → Merchant
The new MDR framework is focused on applicable merchant payments rather than ordinary P2P transfers.
🏦 What About Transferring Money Between Your Own Accounts?
Similarly, transferring money between your own eligible bank accounts through UPI is not converted into a merchant payment simply because the amount is high.
The MDR framework concerns applicable merchant-payment transactions.
📱 Will Google Pay, PhonePe or Other UPI Apps Charge Users?
The reported framework does not introduce a general platform fee that UPI apps can simply charge consumers for routine UPI payments.
Consumers can continue using UPI applications for everyday transactions without a general UPI payment fee.
However, individual apps may have separate charges for unrelated products or services, so users should always check the transaction screen before confirming a payment.
📊 UPI’s Massive Scale in India
UPI has become one of India’s most widely used digital payment systems.
According to the data cited in the report, the UPI network processed approximately 24.51 billion transactions worth ₹29.9 trillion in August 2026.
The scale of the ecosystem explains why even relatively small changes in merchant payment economics can have a significant impact across businesses and payment companies.
NPCI also publishes UPI ecosystem statistics covering transaction volumes and values.
🧠 Why Is MDR Being Introduced?
The MDR framework changes the economics of processing certain merchant UPI transactions.
The broader objective is to create a mechanism through which parts of the payment ecosystem can be compensated for processing merchant transactions while keeping UPI accessible to consumers.
The key distinction is therefore:
Customer
Makes payment → Pays the merchant’s displayed price
Merchant/payment ecosystem
Applicable MDR → Settled within the payment ecosystem
This distinction is important when understanding the new rules.
🔮 What Changes From October 15, 2026?
From October 15, 2026, the new MDR framework for specified UPI merchant transactions is scheduled to take effect.
The broad structure is:
- Up to ₹2,000: No standard MDR
- Above ₹2,000: 0.4% standard MDR for specified merchant transactions
- ₹75,000 and above: ₹300 maximum MDR
- Certain special categories: Different prescribed rates
- P2P UPI: No merchant MDR
- Customer: No general UPI payment fee
The exact MDR can vary according to the applicable merchant category.
🏁 Conclusion
The introduction of MDR on selected UPI merchant transactions does not mean that consumers will suddenly have to pay a UPI fee.
The major change is on the merchant/payment ecosystem side.
For a standard eligible merchant transaction, the MDR is set at 0.4% above ₹2,000, with a ₹300 maximum cap for transactions of ₹75,000 and above.
So:
₹5,000 payment → ₹20 MDR
₹50,000 payment → ₹200 MDR
₹1 lakh payment → ₹300 maximum MDR
But the customer continues to pay the merchant’s listed price under the stated framework.
The distinction between customer payment and merchant-side MDR is therefore the most important thing to understand about the new UPI rules.